About this episode
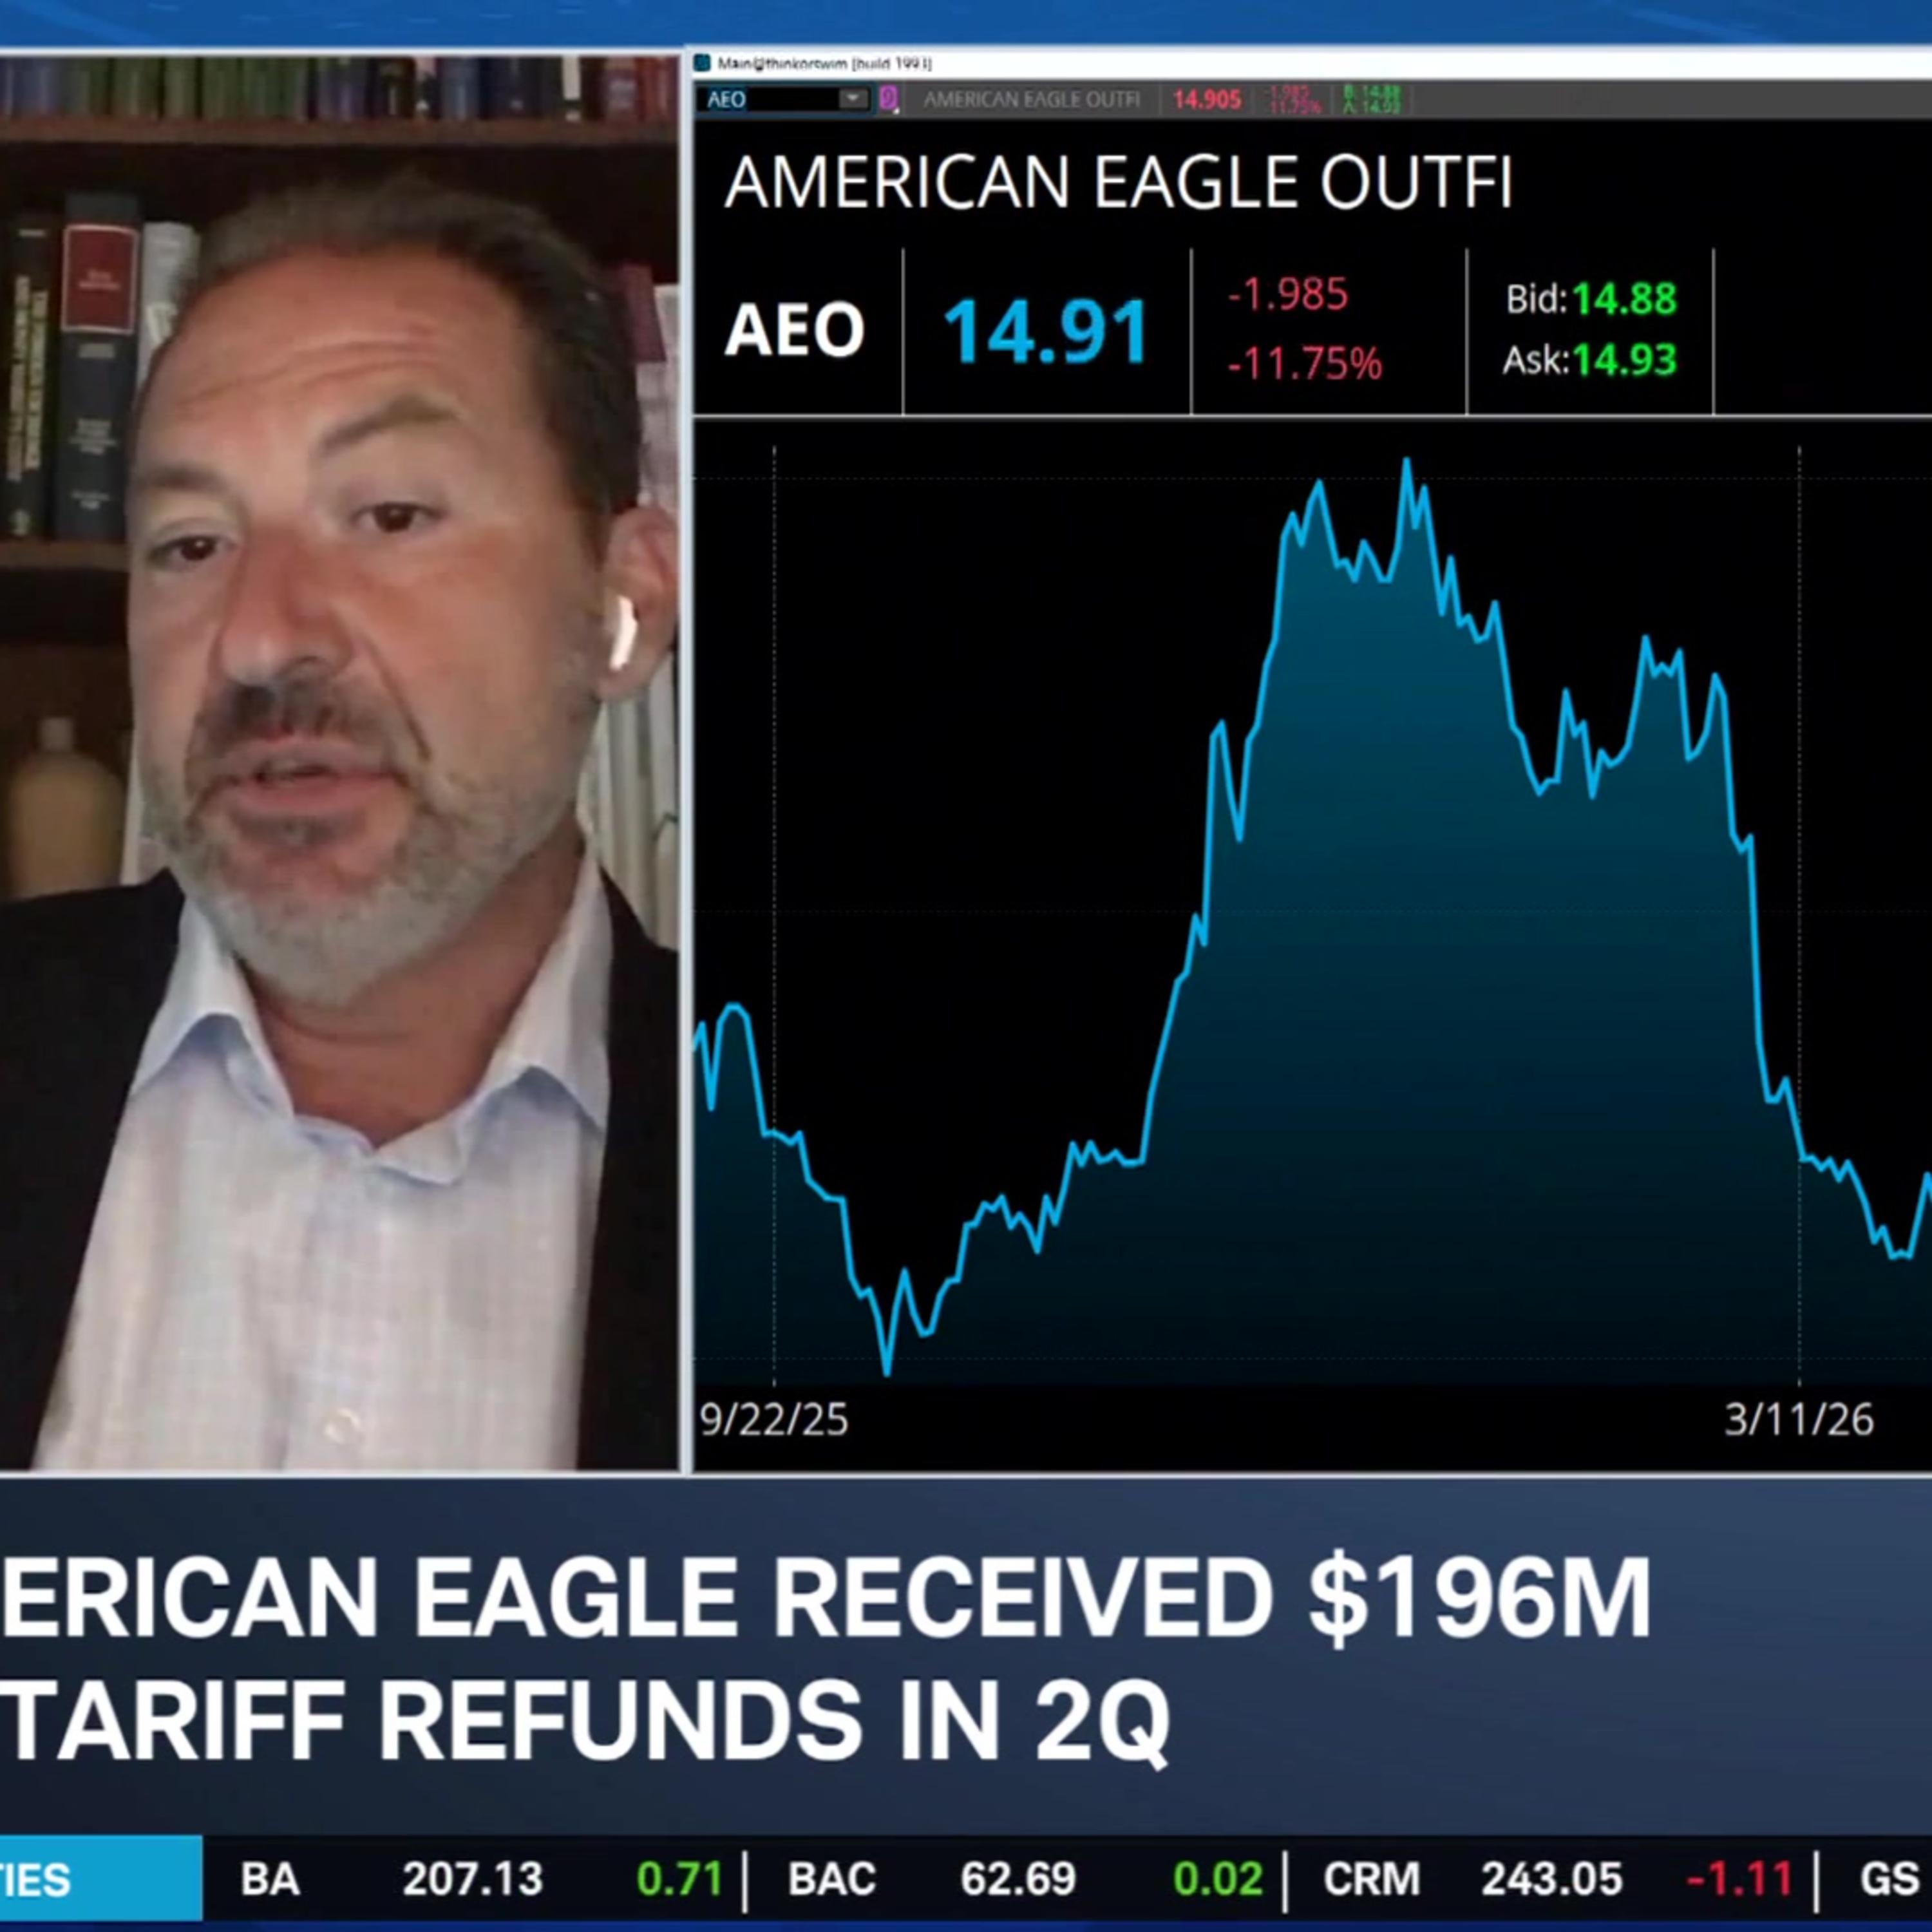
American Eagle Outfitters (AEO) posted a "mixed bag" earnings report, according to George Tsilis, who explains why the clothing retailer company is seeing pressure from pinched U.S. consumers. Macy's (M) also traded lower despite posting an earnings beat and increased full-year guidance. In the healthcare space, Cooper Companies (COO) plunged on a revenue miss and lower guidance.
======== Schwab Network ========
Empowering every investor and trader, every market day.
Subscribe to the Market Minute newsletter - https://schwabnetwork.com/subscribe
Download the iOS app - https://apps.apple.com/us/app/schwab-network/id1460719185
Download the Amazon Fire Tv App - https://www.amazon.com/TD-Ameritrade-Network/dp/B07KRD76C7
Watch on Sling - https://watch.sling.com/1/asset/191928615bd8d47686f94682aefaa007/watch
Watch on Vizio - https://www.vizio.com/en/watchfreeplus-explore
Watch on DistroTV - https://www.distro.tv/live/schwab-network/
Follow us on X – https://twitter.com/schwabnetwork
Follow us on Facebook – https://www.facebook.com/schwabnetwork
Follow us on LinkedIn - https://www.linkedin.com/company/schwab-network/
About Schwab Network - https://schwabnetwork.com/about
Get every episode summarized
Each time Schwab Network publishes, we email you a written briefing from the transcript — the topics, who appeared, and any specific claims, with the ad reads skipped.
Email me new episodesFree for 3 shows. No card needed.
Transcript ready
35 searchable segments. Every word is indexed and playable.
Full transcript
Schwab Network — Thursday's First Moves: AEO, M & COO Sell Off After Earnings. Machine-transcribed; use the interactive transcript above to jump the player to any line.
We have first moves here, senior markets correspondent George Silas is with me and let's talk about some of the movers on Wall Street people want to know all about American Eagle outfiters. Let's start there. Good morning George. Good morning, Nicole. Yes, I'm looking at the price action down around 15% today for American Eagle. They reported earnings and sales as well as comp numbers. It really makes bad if you look at the top line sales that came in slightly higher than estimates of 1.38 billion versus 1.37. So that was higher year by by about 8% EPS actually came in quite a bit higher on adjusted basis is 79 cents versus the 21 cents estimates. So that was higher by around 76% compared to last year at 45 cents. Do we get the total comps they were higher by 6% but the breakdown of the comps makes a difference because the American Eagle comps themselves the core brand was down about 1%.
So that was a bright spot with their area brand at least their offline cost which were higher by 19% but it looks like right now investors aren't too receptive of the area cost which were much better than estimated now they did to note they received around $196 million in tariff refunds. But at the same time they also denote the merchandising margins declined by about 330 basis points. So at the end of the day, you know the area brand itself, my comp standpoint 19% sales 25% for that brand was was good but nonetheless the the AEO comps were down 1% but also the merchandise margin which compressed talks about or tells us essentially that there's inventory hangups. And guidance also came in the mid single digits positive for operating income estimated to be around $550 million on the high end. Yeah, I understood I mean area has continually been the bright spot for American Eagle but the question now is whether or not folks are prioritizing gasoline and groceries over a parro.
Shopping for whatever let's get to Macy's here because this is another retailer's different story to because they have a lot of real estate but let's talk about Macy's. Well, Macy's you know if you look at the numbers themselves there was a strong beat very least on EPS front and sales came in around 4.87 billion versus 4.81 we can see the stock is trading slighted it down side by about 5%. The EPS you know last year was 35 cents they posted 63 cents estimates around 37 cents. Comp sales system wide consensus was 1% they did post as a total business 2.7%. Now if you look at the Macy's comps they beat the total consensus at 1.1 blooming Dell comps up 11.3%. So that was a bright spot and that's typically a little bit more of the flu and higher end consumer bloom mercury also increased by 6.2%. And that's also another Q2 high sales volume number at least for blooming Dell's was the highest Q2 sales ever.
So with that said they did raise their guidance the old guidance for fiscal year 26 sales on the high end was 21.75 billion. They now are posting 21.83 as well as old EPS guidance at 220 on the high end versus now $2.35. So comp sales guidance also increased to approximately 1 to 1.5%. So it may not necessarily be as much as perhaps folks had anticipated but nonetheless gross margins also here appear to be slightly down. So that's also the same case for a EO and I think that's one of the compression compression reasons that we're seeing some some price action move the downside of this name. Pretty surprising to hear blooming Dales had its best quarterly sales ever in this environment or so people are picking and choosing where they're spending it and as you noted that's on the upper end right in the if you want to call it a V shape or K shape whatever.
But the lower end folks are not shopping at blooming Dales as much and Blue Mercury also is more of a high end type of store in that too. Very interesting. What about Cooper companies? This has been a big laggard. I saw it early this morning and the early active numbers to the downside. So looking at it right now it's down about 17.5% or $11. So this is for those who don't know this is a business that is in the medical device space. Have surgical systems would also vision and I'll talk about their their their spin off or what they anticipated to be a spin up which didn't manifest. And I think that's also probably part of the problem here. But if you look at the total top line sales for both divisions together. $1.6 that was down versus the estimates 1.06 billion versus 1.10. The just an EPSB 1.15 billion versus 1.12 that was higher by 4%. But the vision business denoted 717 million revenue was basically flat.
And they also talk about how margin guidance was also expected to be weaker. But also if you look at their surgical organic growth that was 4% to 6%. So their vision division their vision. Business was down the surgical division was higher but the bigger shock I think was also that the surgical division is not being sold. That was anticipated. And that's also creating some some issues with investors right now. But in lieu of that they did initiate a buy back between 2 and 3 billion dollars. But doesn't look like that's very receptive. I'm going to invest for standpoint. Very hard to find winners today. For example, I just pulled up the S&P 500. I was looking at Cooper being the big lag or it and they wondered if they were winners. There's just a handful. You know, Apple, Coca-Cola, Walmart, Johnson and Johnson United Health and travelers and Chevron. Not that many winners today. George Tillis, thank you. Really appreciate it.
More episodes
More from Schwab Network

Stock Market Today: ORCL & ADBE Earnings, AEO Plunges Near 52-Week Low
Schwab Network

Thursday's Final Takeaways: Crude Taps $103 & PPI Hotter than Expected
Schwab Network

Balancing High-Conviction AI With High-Dividend Diversification
Schwab Network

EARNINGS PANEL: ORCL, ADBE
Schwab Network