About this episode
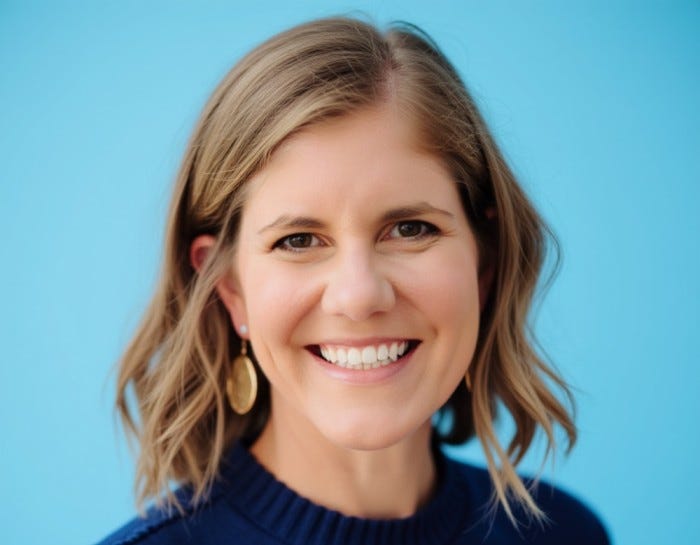
Beth Bafford spent years designing Climate United, a revolving fund meant to push out $7 billion of Greenhouse Gas Reduction Fund money to underserved communities. She had barely begun sending out grants when Trump shut the program down and rescinded all the money. In this episode, I talk with her about that experience, the ongoing legal fight to reclaim some of the money, and the central importance of finance in clean energy policy.
This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit www.volts.wtf/subscribe
Get every episode summarized
Each time Volts publishes, we email you a written briefing from the transcript — the topics, who appeared, and any specific claims, with the ad reads skipped.
Email me new episodesFree for 3 shows. No card needed.
Hosts & guests
Transcript ready
566 searchable segments. Every word is indexed and playable.
Full transcript
Volts — Climate finance, interrupted. Machine-transcribed; use the interactive transcript above to jump the player to any line.
Hello everyone, greetings. This is Volt for April 17th, 2026. Climate Finance Interrupted. I am your host David Roberts. Clean energy has a finance problem. The technologies exist and they are increasingly cheap, but capital still doesn't flow to the places that need it most. Low-income communities, rural areas, projects too small to get on the radar of private lenders. Tax credits don't help if you don't have tax liability, and grants can rarely scale enough to cover the gap. The Biden administration had an ambitious plan to fix that problem. The Greenhouse Gas Reduction Fund, $27 billion seeded into a new ecosystem of revolving funds
and community lenders designed to continuously cycle clean energy capital into underserved markets for decades to come. It was one of the most innovative things in the Inflation Reduction Act and almost nobody paid attention to it. If you want the full deep dive I did an episode back in 2024 with Jahi Wise, the EPA official who designed it. Beth Bafford paid attention, as CEO of Climate United, the coalition that won the single largest chunk of GGRF funding, nearly $7 billion. She spent years designing financial structures, assembling lending partnerships, and generally standing up the organization from scratch. She got about $400 million out the door before the Trump administration froze the accounts and tried to kill the whole program. She has been fighting in court ever since. By the time you hear this she'll have left the job,
her last day is March 31st, so we're taking the opportunity to talk while she's still in the thick of it. What Climate United was trying to build, what the freeze felt like from the inside, and what the whole experience taught her about the role of finance in the energy transition. With no further ado, Beth Bafford, welcome to Vultz. Thank you so much for coming. Thank you for having me. Let's rewind the tape a little bit and go back. This is not really directly your main door, a topic at hand, but I was charmed by it. I went back and read this piece of yours, several years old, about you leaving a high-profile Wall Street job to go volunteer as an unpaid volunteer for the Obama campaign. And you wrote a story about you're on the subway going to quit your job and you hear defying gravity, the song defying gravity on your headphones and it gives you strength.
I just have to say that whole everything about that is just like literally the most millennial thing I've ever encountered in my entire life. I love it. And it really like I had sort of forgotten because of you know, wave's hands at current events. I had kind of forgotten about that whole thing. There are so many people with stories like yours. There's a whole generation of people who were pulled into public service, biobama, and not just public service, but like public service with a smile and some optimism and can do spirit. You know what I mean? That just seems so gone now, but there's a whole generation. And I just wonder like who's pulling the Beths into public service today? Where is that generation now? Do you ever think about that? It's so funny. You say that because yeah, I think about it a lot and I talk about these with friends and colleagues a lot that that's my now my number one kind of criteria for political
candidates is their ability to attract and inspire kind of blindly optimistic talent. Because you know, no matter the side of the aisle or your policy preferences or your governance style, it's really about you know how you govern who you surround yourself with, who's interested, excited to come to work to every day to solve these problems. And I think of it as kind of what I call the the Obama ripple effect. I mean, I have so many friends and colleagues from that time. I mean, I interview people every week and they're everywhere. They're in state government. They're running companies now. They're running NGOs like that Obama diaspora has spread out now and is like, you know, running things and it just doesn't. I don't see a I mean, maybe I'm wrong, but I don't know that I see a wave coming in today in the same way. Yeah, I mean, hopefully we'll be surprised. I do think that that training early
on in your career, I talked to people about careers all the time and that experience and training. Again, not in any way that's overtly political, just the experience of being a part of something working with really inspired and talented people of, you know, for a common goal working your butt off, you know, 20 hours a day and existing on, you know, I think I used to get quadruple shot lattes to make it through the day and the bond that we created with my friends and colleagues at that time is one that still exists 15 years later. So then you worked for Obama for quite a while, ended up in the Obama White House in OMB. So then you went OMB, then you went to McKinsey and then you went to this Calvert Fund. This journey has sort of given you this respect for finance, the under sort of the under appreciated role of finance. Talk about a little bit just about your
experiences before the GGRF, sort of how you learned and what you came to believe about finance as a tool. Yeah, so my eyes were really open to kind of the importance of finance and credit. Actually, when I was an organizer on the campaign and I think something that really struck me was that no matter where I was in the country, when I went to someone's doorstep and we went to thousands of doorsteps and knocking on doors and talking to voters, no matter where they were in the country, urban, rural, suburban, man, woman, race, background, economic status, like people all wanted the same thing. They wanted like a safe place to live for themselves and their family. They wanted a community around themselves that they felt a part of. They wanted a job with dignity and respect and so many of the things that underpin those basic desires are things that
are enabled or not enabled by access to the credit markets. The ability to buy a home by accessing a mortgage. The ability to buy your own a business, you know, by accessing a loan, the ability for businesses to generate and create jobs. The ability for a community to come together and build a community facility or a church or a place to gather, you know, or a health clinic, you know, so many of those things that like that basic community infrastructure really relies on access to credit. You worked in health care for most of that time, right? You were sort of focused on health care. I was focused on health care, yep. We're finance obviously, please a huge, huge absolutely. And so with that kind of in mind, I went to business school after working in the White House and really just used those two years to explore this intersection. I knew that I had this mission in mind and wanted to help people access those basic needs. I knew that I wanted
a kind of finance and business toolkit. My mom's a financial advisor. I've always been interested in the markets and I knew that there was kind of some area that there was intersected but didn't know where I wanted to be. And when I was in business school, I discovered this world of kind of community finance and impact investing and really got obsessed with that intersection. And so when I landed at covered impact, it was just such a dream to be in a place that really specializes and focuses on understanding and addressing these chronic gaps in the credit markets and works with on the ground partners globally to address those gaps in ways that both generate a return, but also importantly kind of demonstrate that these markets are investible. But these are not things that are only required to be filled by philanthropy, but there is a role for the financial markets in building these sectors. And we do that across sectors and affordable housing, small business development, education, healthcare, agriculture, sustainability, and clean energy.
And it was those kind of building blocks and understanding of that, the local ecosystem of financial institutions across the country paired with this centralized infrastructure to really think about market making that led to our interest in applying for the greenhouse gas reduction fund. Well, tell me a little bit about the look to hear that story. So you're working at Calvert doing this work and you apply for some GGRF money and boy, do you get it? What did it feel like to get $7 billion dropped in your lap? Were you don't it? Did that feel crazy? Did that feel inevitable? Were you just excited? Like $7 billion is like kind of blows my mind. I wonder how you what that felt like when it first landed? Yeah, we were so excited. We were so ready. We had been working on the program specifically for years and... Oh, on the GGRF specifically? Yeah, really since the bill was passed. So the IRA was
passed in August of 22. We immediately started, we had kind of been following the legislation, so we immediately started looking at partnerships, strategies, pipeline, trying to really understand what the EPA was going to do with the program, building coalitions and partnerships and conversations. I mean, I probably met with hundreds of organizations that I had known from my job to understand kind of how people were engaging, how people were thinking about leveraging these funds. Were you sort of leading that effort from the beginning? Like, what did you raise your hand to run this thing from the beginning? No, I mean, I was one of hundreds of people that were trying to kind of pick it apart, understand what how it was going to be implemented. I mean, the legislative text is like a page. So there was a lot for the EPA to design and interpret, and so really trying to understand what that was going to look like. We couldn't interact with the EPA, and so it was
really taking the time to develop our own strategy and said, if we were lucky enough to get access to some of these funds, what would we do with it? How would we put it to good use in a way that, optimizes return for taxpayers and really pushes the envelope on the program's objectives, which were reducing greenhouse gas emissions, providing direct benefits to people's lives, and really activating and transforming the financial markets. We can imagine that's a pretty big mandate, and so we worked for about a year to put together our strategy even before the applications opened, because once the applications have been, we only had 90 days to put together, you know, hundreds and hundreds of pages of an application to throw our hat in the ring. Well, let's talk just a little bit then about what climate united was, because I think one of the things I want to clear up a little bit here is I think people have in their heads that it's just a bucket of money that's given to you to spend, and then when you spend it, it's gone. That wasn't
quite right. These are supposed to be revolving funds that are set up as institutions, as enduring infrastructure. So just talk a little bit about sort of the structure of climate united. What is it? Yeah, absolutely. So that is a common misperception that it was just another one of the IRA grant programs, and I really think of it as a bridge between a lot of the grant programs that were just providing direct assistance to projects and communities and all the tax credits and incentives that were out there for the taking by private actors, and we were really meant to be the bridge between the two. How do you intentionally create these financial institutions that are going to communities that otherwise would not be benefiting from the tax credits and incentives? And looking at how to braid those resources with access to credit, to liquidity, to finance projects and businesses that otherwise would not be financed.
Is a lot of that not just deploying your own capital, but trying to attract private capital too? Absolutely. Making it safer, I guess, for private capital. So once we got the requirements from the EPA, that was one of the mandates. Every dollar we invested had to leverage other private capital, and so these funds really went, and I will just break down for a second. The Greenhouse Gas Production Fund had three programs under it, the National Clean Investment Fund, the Clean Communities Investment Accelerator, and the Solar for All Program. And so the program that we were a part of was the National Clean Investment Fund, and that really was the U.S. government seeding three national clean financing entities, including Climate United, by essentially providing the equity on the balance sheet of those institutions that could be levied to the private capital and do transactions in the market that the market is not doing alone. But you are like the seven billion dollars, you weren't just
supposed to spend it down, you're supposed to make it back, like it's supposed to be renewing itself, right? Absolutely. Yeah, so we took a 30-year time frame, really with the objective and really trying to drive the U.S. towards its 2050 goals, and those funds, in our projections, actually got bigger over time, right? We invest, we earn income from those. You're pooled, you're working with gets bigger. Exactly. Interesting, so you start with seven billion, and I'm just curious, I guess maybe it doesn't matter now, but at the end of 30 years, what was that seven billion? How big, how much growth? I don't remember off time I had, but it certainly, obviously depends on different risks we take in different sectors and expect the losses, but even with just the interest earned on the funds right now, it's growing, and so we did expect to see that grow significantly over the next 30 years. So, when I hear about this, I think when ordinary people hear about this, almost everyone has
the same question, which is, if there is a project where you could invest some money and have a reasonable expectation of making your money back and a little profit, why aren't private banks doing it? Why do we need public money? Why, if you are proving that you can make money in these places on these types of projects, why isn't private money doing it instead? Yeah, it's a great question, and it's a very common misperception. I will over generalize here for a second, but I kind of look at the market for, I'll say, clean tech deployment, so adoption of these technologies across sectors in three main buckets. Bucket one is projects or businesses that require subsidy or they won't happen. So those are projects or businesses where the math doesn't work because of things like low cost electricity, high transaction costs, where they're significant technical support needed,
that's expensive, or very small transaction sizes. Solar on churches, in a rural community. A lot of those types of deals really don't pencil unless you have some sort of subsidy in the stack. So you did those kind of deals? So you would subsidize, this wasn't purely money-making play, you would subsidize some kinds of deals? Yes, but typically in the form of lower cost capital than the market would provide. So it's not subsidy in terms of we're giving a grant to the project, it is we are doing a 25-year loan at 4% when the market for that is 12% and that's where you know, some of that is is really needed to make the math work in some of these projects. Bucket two is projects or businesses that benefit from subsidy but are feasible without it. So they're profit-making but not profit-maximizing and those tend to be things, you know,
reasons because of complex financial structures, high perceived risk, limited amount of data available in that market so people don't really know what they're getting. And a good example of that is was the trucking program that we were working on where it actually was a pretty attractive financial profile. If you really understood and kind of got in the weeds of the financial structure but it was really complex and a lot of people didn't want to do the brain damage to figure it out. And that's a lot of the market, right? This is what I close Bucket two is things that are just they're feasible, they're just not low-hanging fruit so they're not on the top of anybody's list if all you care about is profit-maximization. Yeah, that's interesting to think about like in terms of kind of market theory, you know, like private markets are supposed to relentlessly exploit all those all those opportunities, right? It's funny to think that there's a huge sort of tranche at the bottom that's profitable but ignored because it's complicated that it's just sort
of hard to fit that with my image of market efficiency. Well, and it's why a lot of these, what we call kind of specialty green financing organizations have popped up, right? The trend of the banks and the institutional investors, they've gone so far up market because of consolidation and size and transaction costs that it has created this pretty broad opportunity for people to step in who really care about that part of the market and make good money and have strong businesses but there is a pretty big gap that exists and that's why green banks have stepped in, that's why, you know, for-profit specialty finance companies have stepped in. So you go in and absorb the brain damage and then presumably private money follows after that, that's right because the private markets really look for standardized structures, right? Things that have worked before and that will work again or where there is significant
data to show what is expected to happen. And then bucket three? And then bucket three is just things that the private markets will do on their own. So the, you know, utility-scale solar with identified corporate offtake, things that, you know, Brookfield or JP Morgan or TPG or any of the large banks or institutions will do. So you are in the business of trying to tip large industrial scale projects over the threshold into profitability? That's just kind of a different thing. That was not a part of climate united strategy. Our strategy was really how to get bucket one and bucket two done in a way that demonstrated how the market could address these areas, but also in a way that brought some of the, and this is going to sound so wonky, but the centralized market infrastructure that's required to get the large players in. And, you know,
that is not a small feat. And it's also not something that policy typically allows organizations or grantees to do. It was really one of the parts of this program that was unique that it really recognized the need for centralized market infrastructure. If we are going to get the private markets to engage in this way and that's things like standardization of lending products that can help with, you know, aggregate assets, you know, mortgage markets exist because we have standardized mortgage products. Well, this is, I mean, here's a confusion. Like you are taking on what a lot of big private banks won't, which is sifting through a large number of smaller, sometimes marginal projects, right? And there's a reason the big banks don't mess with that is that there's a high, I would imagine, a high sort of transaction cost. There's just a lot of
thinking and paperwork less juice relative to the squeeze. I guess this is how you'd put it. So how do you standardize that? Like you're specifically in the business of looking for these kind of weird, small, not quite, you know, fish, not quite foul projects that private capital isn't doing. How do you take these weird bespoke projects and turn them into something fast and standardized? There's two issues that play there. There's size and then there's kind of the bespoke nature. And there are certain things where you could essentially standardize the product, the financial product, and then allow for much broader aggregation of those products, where you don't need to do one off every time. So an example of this, one of our partners in Climate United is self-help credit union. They do single-family mortgages and have four decades
with the funds from Climate United. They were creating a single-family green mortgage program building off their success in providing first-time home buyers with a low-down payment mortgage. So they offer a 97% LTV mortgage until first-time home buyers and they've proven, over the last 30 years, that those mortgages perform just as well as a typical LTV mortgage. And they were doing the same thing for green mortgages, where they were setting certain standards for the home that it had to, you know, stand on efficiency, electrification, and on-site generation where possible. And if they met those standards, that the homeowner would qualify for this green mortgage product. And then they were using the TDRF funds essentially as a guarantee so that lenders across the country could originate those mortgages, they could purchase and pool them, and they could sell them in the secondary markets backed by this guarantee to basically prove
that these mortgages offering these affordable mortgages to families to buy into efficient households would actually perform even better because of the operational savings of living in a green home. Right. So that's an example where like that's a small ticket size, right, individual mortgages for individual homes. A standardized product where when you have that central market maker, you can really make a big difference if you're able to bridge between the, you know, the home buyer and the secondary mortgage markets. I'm sort of curious like how much of climate United's work was directly with projects versus with things like credit unions that were doing the individual project work, and you're just sort of backing the credit union. You're sort of like funding other funders, do you know what I mean? Is there, is there a split there? Yeah, we were doing all of the above. So we were doing some direct projects where, you know, like our our dryage truck program where we had to do the kind of financial engineering
directly ourselves. We were doing a lot of work with other lenders to really provide liquidity, so it basically loans to other lenders. They could provide these products in their communities. And then we were doing some funky stuff, some, you know, utilization guarantees for charging infrastructure and various other types of products and programs, but it really enabled us to kind of look across all the different market segments that we were trying to serve. So everybody from consumers to small businesses to communities and really figure out what we thought the right mix was based on, you know, where there was existing lending infrastructure and where we needed to complement that. Let's just pretend for a moment that Trump did not come along and steal our money. Was there like a five year or 10 year vision? Did you have particular plans, particular vision for how this thing was going to evolve? Yes. Or is it just like crank
money out the door, you know, day by day? No, absolutely. We had an extremely detailed five year plan that projected out the deployment of the funds. We expected all funds to be deployed in the first five years. And then, you know, a significant amount of recycling of capital thereafter. And, you know, some of the early transactions we were really trying to demonstrate what this was. So that was our, you know, initial goal was, you know, nobody knows what this is. This program is nobody knows how it works. So let's just do some deals to show what role we are playing in the market and who benefits from that. And so we did get some transactions done. But this market transformation goal was always our north star. How are we really looking at the composition of our investments in a way that is bringing the private markets along that is building the data and infrastructure to get to this kind of overall leverage of private capital, which was, you know,
estimated in the hundreds of billions? Yeah. I mean, I just underscoring what you just said, because I feel like this is a key thing that a lot of people don't understand. And, you know, he's hitting it again and again. But this was meant to be infrastructure. Like, there's not just meant to spend down the money. You help the projects that get the money than you're done. You're building your sort of paving roads that private capital will then drive down after you, right? Like, you're changing things in an enduring way, not just handing out money. You're bringing private capital into markets and kind of building markets. So it's much more like, I don't know if people really got that about the GGRF. It wasn't just money. It was institution building and infrastructure building, which was so cool about it. Yeah. I mean, it's certainly why I did the work. And I think is a big issue. I mean, I recently wrote a white paper on some of my kind of reflections on. Yeah, yeah. We're going to get to that in a minute. Yeah, this works. And what we need to learn
from it. But there really was not an understanding of that simple statement that you just made. So February of last year, February 18th, word comes down that the whole thing is being frozen. And furthermore, that money you had already obligated, money that you had already promised, that was just sitting in the bank account getting ready to go out, got seized. I just sort of curious to hear about that day. Like, what were the hardest phone calls you had to make on that day? Oh, man, there were so many. Um, so we first learned about this from a tweet that went out from the EPA. Oh, my freaking god, are you serious? You the CEO of Climate United learned about this from a tweet? Yes. EPA administrator put out a video that basically said that he was freezing
the program, said that he was investigating issues of fraud waste and abuse and expected criminal activity or criminal structure. I watched that video, uh, at about, I think it was about 9 p.m. I had just put my kids to bed. I was sitting in bed like I often do on my laptop, uh, after they left the sleep and watched the video. He named us in the video as the largest recipient. Really? And so, Nibis has said that was a long night. Um, and lots of conversations with my colleagues, our partners, our communications folks, really trying to understand kind of what it all meant. First and foremost, you know, like any leader in this scenario, my concern was about and the safety of our team. Yeah, I mean, apart from the program itself and all the, you know, the policy merits and everything else, like I can only assume when one of these guys says your name
and one of these videos, you get a bunch of incoming cooks and threats and stuff. I mean, this is a very familiar story at this part. I'm assuming that was part of your experience. That was, unfortunately, uh, it was for, for many weeks. And at that point, this was when all of the dough stuff was happening, you know, it's just, there was a lot going on, a lot of confusion and fear. And so that was a big part of the initial, you know, response. And I'm curious, like, at what point are you forced? I mean, this is the very first thing I thought of when I heard about office, like at what point were you forced to call these low-income communities, these rural communities, these people who I'm sure had been celebrating, getting some money from the federal government and tell them, you know, psych, we said we're giving you money, we said it was a done deal. Now it's not like, when did you make those phone calls? Yeah, I mean, those had to
happen pretty quickly after we realized that the funds were frozen. And, you know, luckily, we have the best, we have a community team that is kind of best in the business that was managing a lot of those relationships. And, you know, just started picking up the phone and calling people and saying, here's what's happening, here's what we know, here's what we don't know, here's what we're expecting, you know, to happen. But we had a program that I haven't mentioned, but we were doing a pre-development grant program for tribal clean energy projects. And we had selected 20, it was 22 projects to get pre-development grants to basically help projects do the assessment and feasibility and community engagement work to develop an actual project in their communities. We had told those 22 people that they were receiving grants, we were in the process of finalizing paperwork to get them out the door and none of those grants got done. And so, you know, that
was and has been the most painful part of this process. Obviously, there's been a lot of pain, but the number of organizations across the country that were working with us or one of the other seven awardees who were doing this work, I mean, there's just hundreds and hundreds of organizations that had done a ton of work to envision what clean technology adoption looked like for them in their communities, whether it was, you know, solar on community health centers or supporting rebuilding of homes after Hurricane Helene or, you know, these amazing tribal sovereignty projects in Alaska. I mean, this is work that was underway in every corner of the country with so many community organizations and they were just as gobsmacked as we were. And it's just like, I don't even know how to describe it. It's like you've particularly selected group of the most vulnerable, the most hopeful, the most, you know, helpless to control what the
federal government does. Just like you could not screw up a more undeserving class of people. I mean, I guess that's just the story of the last few years. So I just have to ask like, you know, you put years of your life into building this thing, all this work trying to do good, trying to spread good in the world, you made all these deals, got all these people's hopes up, and then like it's yanked out from under you. You are forced to turn around and screw all these people now. Like you're forced to disappoint the very people you're trying to help. You're accused of criminal activity in a freaking video having never been contacted. I know you're not allowed. I know you don't have probably don't have any time, but like, are you not just pissed off? I mean, I will certainly say I've had those moments and those days, but it is certainly obviously we've been out front in a lot of this, but I'm certainly not alone. There are so many other
leaders and people across organizations that have been going through the same thing, and I found real partnership and solidarity with all of them. I also, you know, what has kept me hopeful is that so many of those organizations that you just mentioned, the people in communities across the country doing these projects and planning and, you know, they're forging ahead. Yeah. This was a setback. It was a surprise to all of us in terms of its kind of severity. But people aren't giving up. I mean, these these technology, you know, we're working on solar and storage and electric vehicles and building decarbonization. Those technologies are better for their health, better for their wallets, better for their communities, in most cases, better customer experience, and and people are figuring out how to make it happen. Yes, I can't tell you how many conversations of exactly this form I've had though over the past few years. Like, oh, you took an enormous body blow. Yes, but we're not dead yet. We're still we're still
limping forward. You know, I guess that's glass half full. That's that Obama optimism coming back out. Well, let's talk a little bit about the legal fight over this. I mean, it's just yet another thing that baffles me like this money was obligated, which means it had been granted by the government. It was given to you. You had it in your bank account. So like we still do. We still do. So like still there. Yeah. The federal government coming back and taking back money that it already gave to you is just very straight forwardly illegal. So what is going on here? What is the substance of this case? I tried to do a little digging into the history of the government's arguments in your case. And it is like trying to pin down a wet bar of soap with your finger. They just like the arguments seem to shift and morph as you're looking at them. So just like can you
just briefly catch us up on the legal fight here? So just quickly on the timeline. So we went three weeks after the funds were frozen without hearing anything from Citibank, which is where the funds are held or the EPA. So this video was all you knew or heard about it for three weeks. They didn't know what in the government called you or contacted you. Nope. God, that is bizarre. Yeah. So all we knew is that we were asking for funds and we were not receiving them. And the way the program was structured is that we were only allowed to draw funds for immediate needs in the next 14 business days. So we didn't have kind of reserves that we had drawn out of our accounts that we could use for ongoing operating. So after three weeks, we were basically out of money. And so we filed suit on March 8th last year and asked the district court to step in. We were successful in that initial. Right. The first district court said, yes, this obviously illegal
thing is obviously illegal. Yes, that's a great summary. So she issued a initially issued a temporary restraining order to make sure that the funds wouldn't move. And then she issued a preliminary injunction in April that said, this is illegal. The program should be open and the funds should be flowing. The administration immediately appealed that decision and the appeals court put a stay on the preliminary injunction, which basically meant that the program was not open and the funds could not flow until the appeals court made its decision. That the appeals court judges. It was a three judge panel who was considering the appeal to those judges for Trump appointees. One was an Obama appointee. And that appeals court essentially overturned the preliminary injunction. And I know I'm getting a lot of legalese here, but over. These are like double triple negative negatives at this point. It is. I feel like I've gotten three law degrees in the last two. But basically overturned it. But not on the basis that the judge
was wrong that it wasn't an illegal act. But on the basis that the case should be tried in another court. What? Why? Yeah. So what happened was the very basic legal argument of the government after they realized that there was no legitimate reason to terminate the program was that this was a contractual dispute, not a dispute that deserved to be in the district court. Oh, good. And so this is a very kind of wonky legal issue. But when you are in a contractual dispute with the US government, there is a court that hears those claims called the Court of Federal claims. It's basically like contract court for the US government. And so if you are bringing a pure contractual claim, it is meant to be heard in that court. And our argument is that it was not purely a contractual claim that there were issues of regulatory, you know, they broke regulation, they broke the law,
and they did actions that were against the articles of the Constitution. I mean, they violated a statute that seems like more than contractual law. I mean, what do I know? I'm not a lawyer either. Yes. So we argued and are still arguing that it violated a statute, it violated the EPA's own regulations and it violated the Constitution. And because of that, we do belong in this court, because this is the only court that can hear those claims. And is that where things are now? So we heard from the appeals panel in September. We immediately asked the full appeals court to re-hear the case. So there is this interesting kind of mechanism where if a panel, a smaller panel of judges makes a decision that the full court doesn't agree with, the full court can step in and say, hey, we don't agree with what these few judges. Is that an unbunk? Unbunk? Yes. We're all learning. I know. I know. So the full appeals court, because, let me just impact that a little bit,
because the small panel made a decision that was obviously crazy, the unbanked panels stepped in. Your words not mine. And said what? The panel had said that we did not have jurisdiction in district court. We needed to go to the court of federal claims. And the unbunked court, the full court stepped in and said, no, we don't agree. And so they are hearing that right now. So we heard that they were going to take the case in December. We had a hearing about a month ago. Wait, they're going to hear whether to hear the case in their court soon, or they're going to hear the case in their court soon. So they are basically deciding whether or not the district court has jurisdiction to keep this case. Got it. And as I understand it, the argument from the government now has gotten, if anything, more Kafka-esque, the argument now is, as I understand it, like every judge who's looked at it says, yeah, that was illegal. It's just not, you know,
it's not an ambiguous case. But now the argument is it might have been illegal, but we killed the GGRF by statute with the OBBB, the big, beautiful bill, killed the GGRF. So the argument now is, yes, we illegally seized the funds, but because the program is dead now, there's no remedy. There's nothing you can do about it. It's too late, too bad, suck it up. Is that basically the government's argument now? Yes, I mean, they're basically saying that we argue that by terminating the program, they broke the law because they're not running this provision of the IRA, and they're saying, well, now that provision is no longer. And so it is nice. So they're basically trying to say that the OBBBA retroactively repealed that part of the statute, which our lawyers argue is not the case. Yeah, and let's just unpack this. If a court says here to a political party,
yeah, you can break the law as long as you get the law off the books before we hear about it, you're scot free. That seems like a terrible precedent. That seems like a terrible thing to say to the government. Yes, there are a lot of tough precedents here, and there is a lot of precedent to say that this legislation can and should not be looked at as retroactive. And if so, Congress has to explicitly state that, and it's pretty clear from the congressional record and all the negotiations that were happening around the passage of the OBBBA that that was not the intent, that they were trying to rescind the unobligated funds and kind of take the program out the books going forward, but certainly not meant to interfere or interact with the you know, program that was already underway. So sequence of events this full on bank on box is going to hear and decide whether you're going to be heard in district court. So if that
goes well, then you'll be heard in district court. And if that goes well, then what what is best case scenario here? Like what amount of money are we talking about? What was is this all about the money that was obligated, but not yet out the door? So it's all about the money that is currently stuck in our accounts. Right. How much is that? For us, it's now well over 7 billion because of the interest it's been earning. But that all that 7 billion wasn't obligated yet, was it? Like you would only sort of promised a fraction of it. Am I wrong? So all of the 7 billion was dispersed into our accounts. So typically how the government awards grants is that they essentially obligate the funds and then you draw them down as you need them to invest into projects. But because this program was built to capitalize an investment program, we needed those assets to be on our balance sheet so that we could leverage them. And so the government, we actually took all the funds
out of treasury, put them in our accounts. And then there were certain rules around how we could use those funds for qualified, you know, projects and expenses. And so the funds were all out of the government, which is why this is even, you know, a little bit crazier. Yeah. I mean, really this is the federal government reaching into the bank account of a private non-government organization. And basically stealing money. I mean, it's not theirs anymore. It's yours now. So like, it just seems like straightforward theft. I'm just again, I mean, I don't just circling around this again. I was just like baffled like, what is even the argument here? I can't believe this is like limping along in the courts. Especially since every judge who looks at the merits is like, yeah, no, that's super illegal. Campus, every one of them. Yeah. And I think that's my, you know, one of my big learnings throughout this process. Now that I have a little bit of a benefit of time is that, you know, they kind of, they did this all very quickly. And let me
expect that there would be an as quickly of a remedy. We'd be able to, you know, break fast, fix fast. And I think what we're learning, not just in this program, but across the, you know, really all of society. Exactly. Is that that's not how our system works. You know, it's not how the system is set up. And you can, you know, unfortunately, you can break things really fast. And it takes significant time to put the pieces back together. And so I still have hope and a lot of optimism that we will access these funds at some point in the future. Best case scenario is you get your full seven billion that's in your bank account. And you get to start doing what you were going to do with it. Like best case scenario, you get to run the full planned program that you were planning all along. Like, is that the, is that the best case scenario here? That certainly is the best case scenario. Although you can't ignore the fact that this will
likely end up in front of the Supreme Court. And the Supreme Court is a very uncertain place. A court where they're likely to say, yeah, it was illegal, but you know what? He's the president. He's allowed to do illegal things. So you'll hear District Court. Maybe they'll find in your favor. Then it'll go up to the Supreme Court. And we genuinely don't know. I mean, I guess no one really knows what the Supreme Court, but like, we don't have a good sense how they'll take it one way or the other. We really don't. I mean, is anybody prognosticating here? So again, if it goes to the Supreme Court, it will still be on this question of jurisdiction. Oh, it's not the question of kind of the merit of the case. It's still this question of jurisdiction. And so there, you know, there are some inclinations from other cases that have gone through over the last year, some bright spots, some not so bright spots. So it really is anyone's guess at this point. If you get consigned to the contractual court, whatever it is, you said it was called,
what's best case scenario there? Like, could you still win all your money back through that court? Or is that a different thing? Yes. So if we go to the Court of Federal Planes, which is the contract court, you're essentially suing for damages. So at that point, the program itself, like you would essentially say, the program has been terminated, but we are suing for damages because of contractual breach by the federal government. And depending on which lawyer you ask, we could get access to a significant amount of funds through that process. Not like $7 billion. So if by reading, I mean, by the pure reading of the contract, we would be owed all $7 billion plus the accrued interest in what they call expectation damages. So there certainly is a case to make that we would be owed all of those funds. That court is not a fast court. And so, you know, that's another, I would say, two to five years. Oh, jeez. So this is like, at the very least, your funds, I mean, even best case scenario,
are not going to start getting out of the door for years to come. I will say the one thing I've learned is not to try to predict the twist. Who knows what video the EPA will put out tomorrow? It was this process, but it does, you know, it is a long road. It's a long road that, you know, we as institutions and organizations are committed to walking down, but I do think it will be some time before we access funds. So you're handing off all of this now, presumably to someone else. Like, what are you, are you, where are you going and what is your connection going to be to all this once you're gone? Yeah. So I am leaving covered impact after 12 years, which is, you know, certainly better sweet, but the organization has been around for 30 plus years. It will continue to do a lot of amazing work, including kind of shepherd this process alongside of our partners at self-help and CPC, which are two coalition partners. So that work will continue. I will
stay on as a pro bono advisor to the organization to make sure that we get to a good outcome and to make sure there's continuity in kind of knowledge and experience of the last few years. But I had an opportunity that I couldn't pass up to go join my mother as an advisor and support her and her team in kind of the last stage of her career. Oh, fun. And so we'll be going to join her at RBC wealth management and trying to get more money invested in the things that we all care about. Oh, you're going to go be a rich person whisperer. I'm not sure I'd say that, but I will be I really want like I'll tell you one of the one of the pods I've always wanted to do is I've always wanted someone in that world, someone who advises wealthy families on what to do with their money to like come on the pod anonymously, you know, with like a voice disguise or whatever. And like tell me what that world looks like from the inside. I'm so curious.
Yeah, I mean, I think one of the things I'm really excited about is that there is enormous interest amongst investors and people with wealth in engaging in this world, whatever you want to call it, impact investing, responsible investing, sustainable investing, enormous interest and appetite. There is enormous opportunity on the ground of organizations doing really great work in these spaces. But the infrastructure between the two is still very broken. Yeah, yeah. And so, you know, the ability to take my last 12 years of kind of understanding how to activate and invest in areas of kind of broken markets. Now taking that into a large financial institution and really understanding kind of how to pick apart those gaps and how to start to put the pieces together is something I'm really excited about. And, you know, where I see enormous opportunity, plus the opportunity to work with my mom is special for me. She's been my
kind of professional and personal idol for a long time. That's awesome. Well, by way of wrapping up, you know, you made a good case for the important role of finance in this whole world. The federal government is going to be out of that game at least for several years. Let's say probably and who knows maybe longer. So, what can cities and states and private institutions do to fill this gap? I mean, I always come back to this like the very basic foundational fact that the US federal government can print money. So, can't spend all it wants and has access to this basically bottomless well of money. But cities and states don't. So, like, how do non-federal entities step in and try to do some of this work? Yeah, and I think this is where we learned a lot about the importance of these public-private partnerships and kind of the benefits of, you know, what the public sector can and should bring in their unique qualities and the benefits of what the private
sector can and should bring. And the public sector, even if they don't have just pure grant dollars, can do a lot in providing liquidity to local financial institutions to do this work. The ability to create revolving loan fund programs or provide low-cost capital to local whether it's a loan fund or a green bank or a credit union, you know, people can take those funds and do amazing things with it to get these projects done that otherwise are not getting done in the traditional markets. They can also help bring convening power and state and local policies that incentivize this activity. They can, you know, help provide tax credits and incentives locally. You know, there are a lot of things that state and local governments can do to really activate that financial infrastructure that was either existed before the greenhouse gas production fund or has been built since. And I think that's what we've been really trying to promote in the ecosystem is, you know,
there were years and years of planning and pipelines and projects and relationships that have been built. All that work has created value, like surely it's still, some of that, a lot of value is still out there. It's going to come to something. All these projects that did all this planning, all these communities that did all this planning, like surely something's going to come out of all that even if it's not federal money. Yes, absolutely. And that will be a, you know, a positive effect that will endure and will get activated once, you know, some of these funds are unfrozen or once future policy is set. And I think that's important no matter what. And I think the other thing is really thinking about how to just show incremental progress so that people understand what this looks like. Yeah, I meant to ask this earlier, one of the sort of critiques of Ira of the inflation reduction act and the whole Biden administration is that yes, the legislation was great, but the infrastructure required to implement all of it was rickety. And thus,
basically like didn't get enough money out the door fast enough to make a big enough impression on the public to make any political difference. So I just wonder, like from your little corner of the world, do you think you could have gone faster or that the GGRF could have gone faster? Is that a critique that you share or do you think that like it was moving as fast as it could have moved? I think it's a little bit of both. I think we certainly could have moved faster, you know, the process from the legislation passing to the awards was almost two years. So that's, you know, two years lost in terms of showing, you know, demonstration of what this is and showing real benefits to people's lives. So yes, the administration needed to take some of that time to make sure they did it right and they did it well. So that is, you know, certainly not a critique of the administration putting things together, but, you know, every day that funds are not getting out there, that people aren't seeing the projects, that you don't see the ribbon cuttings, that you don't,
you know, see your lower energy bills because of these investments was, you know, a day lost in terms of people really connecting the dots between the policy and their everyday lives. And so, you know, that's part of the reason why we were building so much while we were waiting for guidance from the administration, because we knew that there was going to be pressure to get things done quickly. Let's say DIMS take everything in 28, trifecta, and you have a federal government that is eager to get back in the decarbonization game. And they came to you and said, Beth, we want to do something like the GGRF, but like bigger. Let's blow it out this time. Do you feel like you at this point, like, with all your work and all your sort of insight at this point, do you feel like you could step in and be like, yes, I know how to build this thing so it could rock and roll? Do you feel like you would be ready to go at it again? Yes, absolutely. I mean, it's, and it's not just me, you know, there are a lot of people who
have been involved in building this infrastructure. And we have a lot of lessons learned. We've, you know, made the mistakes. We've learned from them. We've figured out, you know, where the bodies are buried. So you think you could get it up and run in faster this time? Yes. Interesting. Well, maybe someday you'll get the chance. All right. Well, Beth, this is super interesting, super fascinating. I've been wondering sort of what it looked like from the inside of that. You know, there's so many things going on these days. So many, so many horrors, you know, some of the smaller horrors get lost, I think, in the news rush. And I just felt like in our world, this is one of the most maddening things, one of the most promising things that was getting built. And one of the most sort of like baseless, grossly illegal moves on Trump's part. So anyway, I just wanted to put a little spotlight on it. Thank you for coming on and walking us through it. And good luck working with your mom. That sounds fun. Thank you so much David. I'm a huge fan of the podcast and your work and appreciate the opportunity to talk to you.
Thank you for listening to Volts. It takes a village to make this podcast work. Shout out especially to my super producer, Kyle McDonald, who makes me and my guests sound smart every week. And it is all supported entirely by listeners like you. So if you value conversations like this, please consider joining our community of paid subscribers at Volts.wtf or leaving a nice review or telling a friend about Volts or all three. Thanks so much and I'll see you next time.
More episodes
More from Volts
Best of August 2026
Volts
How to respond to disinformation about clean energy, at scale
Volts
Could we use Trump's tricks to make good green policy?
Volts
Making data centers flexible so they can serve the grid rather than stress it ou...
Volts